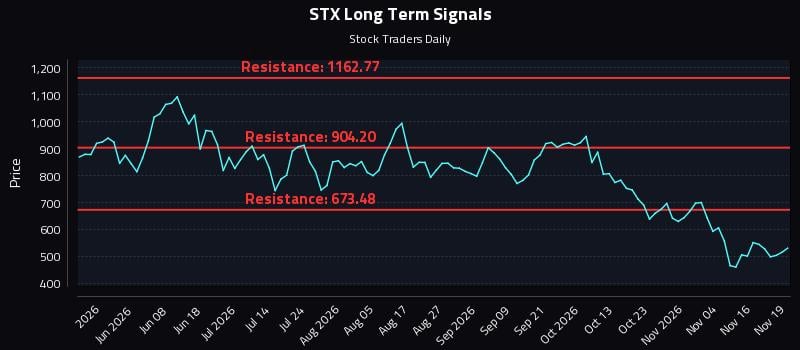
Lam Research came under notable selling pressure as broader sentiment across the semiconductor capital equipment sector turned defensive, driven by a confluence of cyclical reassessments and geopolitical headwinds. As a leading supplier of critical etch and deposition systems, the company is directly tied to global wafer fabrication spending, leaving its valuation sensitive to shifts in institutional risk appetite and near-term capital expenditure visibility across the semiconductor supply chain.
A key catalyst weighing on the stock is ongoing market digestion of management guidance regarding regional demand and shipment timing. While recent quarterly revenue and profitability demonstrated solid operational execution, forward outlooks…