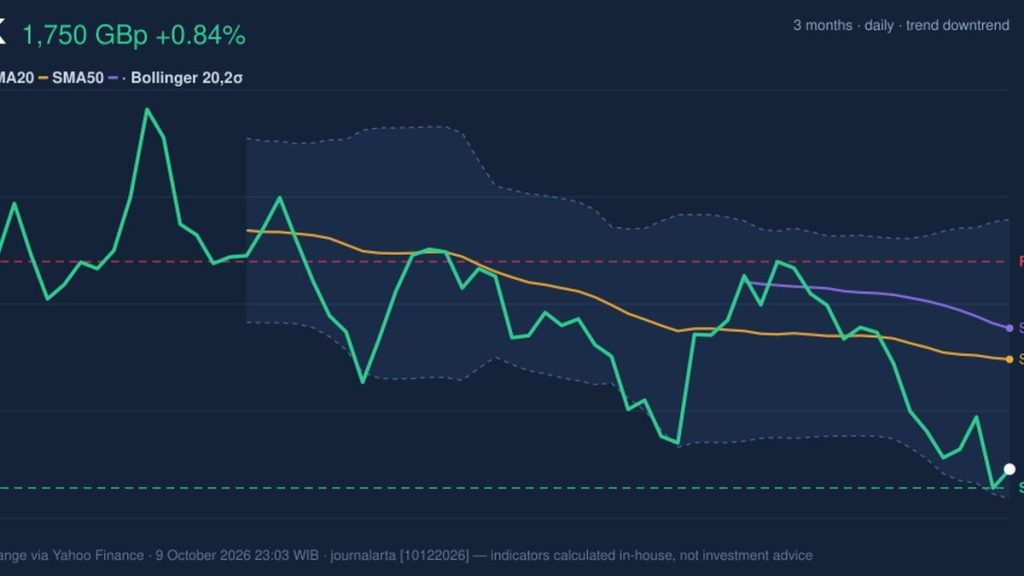
Maruzen’s share price has drifted lower in recent weeks, with the stock down about 3% over the past month despite a solid industrial backdrop. The fresh Q2 numbers now put that slide under a harsher light. Earnings per share landed at ¥81.15 on revenue of ¥17,562 million, while the trailing P/E sits at 11.7x, below both peers and the broader Japan machinery group. The tension for investors is clear: near term softness in quarterly profit meets a multi year record that still points to strong earnings quality and a valuation that many will view as discounted.
Love Maruzen’s earnings quality and sub group P/E but worried the recent share price drift could signal a value trap instead of a bargain? Check the 13 high quality undervalued…